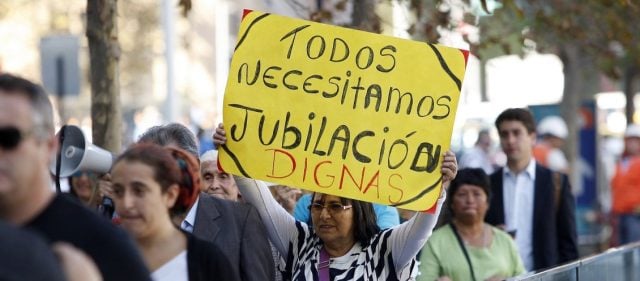
Original article: Todo legal y con plata ajena: el Estado permitió apuestas de las AFP que dejaron pérdidas por US$10.000 millones
For two decades, the State progressively expanded the legal framework allowing AFPs to invest workers’ savings in speculative instruments, culminating in pension funds suffering losses exceeding $10 billion by September 2026.
Figures presented to the Senate by Pension Superintendent Joaquín Cortez indicate that this significant financial collapse not only immediately reduced the retirement calculations for 360,000 individuals nearing retirement but also adversely affected the annual recalculation for an additional 85,000 pensioners under programmed withdrawal plans.
The paradox is that the pension fund administrators broke no laws; rather, as reported by CIPER, they wagered with retirement savings under a regulatory framework established by the State over the past two decades.
«The State allowed this through the enactment of rules and regulations that weren’t even approved by Congress, as current regulations permit,» the investigative media outlet stated.
Risks Associated with Swap Operations
Between January and September 2026, the Chilean pension system faced a dramatic decline in profitability among supposedly conservative funds, as they were exposed to risky, unstable, and long-term financial instruments known as swaps. In simple terms, these are contracts whereby two parties agree to exchange payment flows generated by their respective positions: the first transfers the payments of its instrument to the second and receives, in return, those from the latter’s position.
In such financial agreements, one party pays a fixed interest rate while receiving a variable interest rate from the other, making economic outcomes favorable for one party while detrimental to the other based on market fluctuations. Specifically, the AFPs aligned with domestic and foreign banks to pay a variable rate while receiving a fixed one, anticipating that U.S. interest rates would fall below their cost. However, the opposite occurred, forcing the pension entities to cover these losses using contributors’ funds.
CIPER noted that while Law 19.031 of 1994 initially authorized the AFPs to use these instruments solely for shielding against potential financial risks, a series of administrative modifications transformed this defensive tool into a long-term speculation vehicle, exposing retirement savings to extreme volatility.
This regulatory easing was accomplished through decrees and resolutions crafted by the Superintendence of Pensions and approved by various finance ministers over the past twenty years, bypassing Congressional approval.
Three Key Milestones in Deregulation
Academics and experts consulted by the investigative media identified three key milestones in this deregulation process. The first occurred in October 2008 with Resolution No. 24, which empowered administrators to invest in forwards and currency and interest rate swaps for profit rather than solely for coverage purposes.
Economist Roberto Bonifaz explained that this measure “opened the risk of taking positions with derivatives, limited by a cap that measured amount rather than duration, but which was equal from Fund A to Fund E.”
The second turning point arrived in June 2012, when Resolution 46 and General Standard 69 delegated risk policy control to the boards and investment committees of each AFP, eliminating any regulatory caps on losses, as warned by University of Santiago academic, Víctor Silva.
Finally, in May 2019, General Standard 242 solidified exposure to financial danger. According to Bonifaz, this provision allowed “investment derivatives with the same underlying asset to be offset ‘regardless of maturity dates.’”
From an accounting perspective, this meant that a twenty-year swap contract could be offset with another set to expire in just three months, “even though the former posed a far greater risk than the latter” due to significant long-term fluctuations.
Under these legal allowances, the exposure of Chilean funds escalated during the current decade. According to data from the Central Bank cited by Bonifaz, contracts for swaps on foreign interest rates surged from a reference amount of $3.286 billion in January 2022 to an astounding $270.713 billion by December 2025.
This financial explosion completely distorted the nature of the more conservative mult funds. With no differentiated limits by fund or restrictions on investment duration, Funds D and E—meant for those nearing retirement—ended up taking on even greater risks than Fund C, contradicting the basic logic of safeguarding retirement savings.
For José Luis Ruiz, former main advisor of the Investment Technical Council from 2019 to 2023, the administrators committed serious management failures. “Given that the AFP’s legal mandate is to invest in instruments that ensure adequate safety and profitability, a fundamental error was concentrating management on maximizing expected returns, neglecting risk control,” the academic notes.
In statements to CIPER, Ruiz emphasized that “the AFPs also failed to manage the risk graduation between the different multi-funds, which should decrease in an orderly manner from Fund A (highest risk) to Fund E (lowest risk),” warning that it’s insufficient to limit equity income to 5% in Fund E without managing its internal risks.
Warnings from the Central Bank
The ramifications of these bets extend beyond individual harm to future retirees and pose a threat to national economic stability. Since 2024, the Central Bank had been warning in its Financial Stability Reports that this shift in portfolio significantly increased short-term debt levels and could lead to serious «tensions» in the market.
The issuing institute alerted in November 2025 that, due to losses in these operations, AFPs were in urgent need of liquidity to meet guarantees for international banking, forcing them to liquidate their safest assets in Chile, like local fixed-income bonds, which raised interest rates and hindered growth and employment.
However, it was only in April of this year, after two years of alerts, that the Superintendence issued Resolution 549 and Standard 362 to set limits on potential losses in derivatives, a regulatory shift that, in the words of academic Víctor Silva, “ends opacity and the regulator can monitor [risk exposure] every week.”
Obtén tu Pasaporte y apoya a El Ciudadano
Elimina la publicidad, accede a contenido exclusivo y sé parte de la comunidad.
Cancela en cualquier momento · Sin permanencia