Original article: Venta masiva de deuda en Francia: Desconfianza de los inversores en la sostenibilidad fiscal a largo plazo
10-year yields approach 5% and CDS hit 2013 highs as social unrest highlights political paralysis threatening Paris’ fiscal consolidation plan.
The Citizen
French sovereign debt is experiencing one of the most severe sell-offs since the euro crisis. International investors have issued a strong verdict on the second-largest economy in the eurozone’s ability to correct its deteriorating public finances: long-term financing costs have surged to levels unseen in over two decades, and insurance against sovereign default is trading at rates reminiscent of the darkest days of 2013.
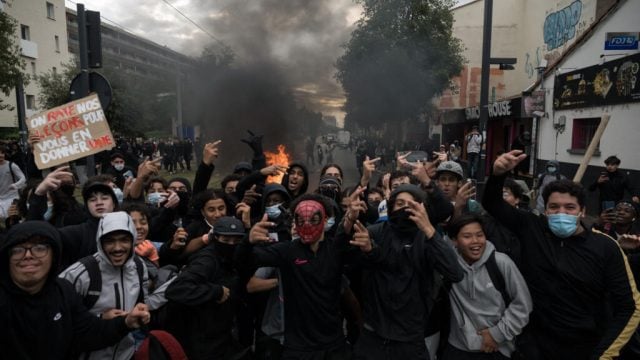
The spark that accelerated this movement was the social explosion over the weekend. Massive protests over the cost of living, inflation, and declining public services led to widespread destruction, looting, and thousands of arrests in major French cities. Authorities imposed nighttime curfews in urban centers like Paris and Nice to contain the violence. However, what began as a social protest rapidly transformed into a market assessment of the French state’s solvency. There are those who may point fingers at the mobilized populace for poor French governance and a tax reform that has failed to address wealthy evaders, the country’s oligarchy.
Market Indicators: Yields and CDS in Alert Zone
The numbers from Monday are telling. The yield on the 2-year French bond, the most sensitive to ECB monetary policy, soared to 3.647%. The benchmark 10-year bond climbed to 4.925%, marking its largest daily jump in nearly a month. Along the longer end of the curve, the 30-year bond—the benchmark for the state’s structural financing cost—exceeded 5.42%.
The most revealing movement, however, is in the derivatives market. The cost to insure French debt against default over five years, measured through Credit Default Swaps (CDS), approached 79.05 basis points, nearing its highest levels since the peak of the European sovereign debt crisis in 2013. Analysts at Macquarie have noted that the price of CDS suggests that the widening spread between French and German debt reflects a real increase in sovereign default risk, rather than just a liquidity premium.
The yield curve has steepened by approximately 130 basis points, indicating that investors are punishing the long-term picture: they demand a significantly higher premium to lend to France for a decade, as doubts linger about the country’s ability to reverse its fiscal trajectory. The OAT-Bund spread—the premium paid for French debt versus the German safe haven—has widened to 146-147 basis points, levels not seen since the euro crisis erupted.
Underlying Fiscal Crisis: A Deficit of 5.4% and Debt Approaching 122% of GDP
The unrest is not the root cause of the problem but rather a catalyst that has exposed a reality that markets have been pricing in for months. France is grappling with a budget deficit of 5.4% of GDP, significantly above the 3% limit mandated by European rules. The debt-to-GDP ratio is projected to hit 122% next year, up from the current 119%, according to analyst forecasts. Economic growth is weak—estimated at just 0.5% for this year—which makes it almost impossible for the economy to expand sufficiently to dilute the debt burden.
The government is acutely aware of the urgency. Prime Minister Sébastien Lecornu has introduced a plan aiming to reduce the deficit to 5% by 2026 through a tightening of €54 billion, focusing cuts on pensions and current spending while increasing the defense budget by €6.5 billion. However, the administration has already lowered its expectations: the initial target of a 4.7% deficit has been abandoned as unattainable. Additionally, the cost of servicing the debt has become a burden: it is estimated that this year France will pay €65 billion in interest, a 25% increase from 2025, an amount that exceeds the education or defense budgets.
Contagion Spreads: From German Bund to Euro and Stock Market
The crisis of trust in France is not an isolated phenomenon. Fears quickly spread to benchmark debt markets. The yield on the 10-year German Bund, the eurozone’s risk-free asset, rose to 3.450%, marking its largest daily increase in almost a month, in a movement traders attribute to cross-selling and a search for liquidity. Borrowing costs in southern Europe—Spain and Italy—also experienced upward pressure, with the spread between French and Italian debt reaching a new record.
The single currency also took a hit. The euro fell to its lowest level in 17 months against the British pound and dropped 0.4% against the dollar, reaching $1.1197. In equities, the Paris CAC 40 tumbled 1.5%, extending the losses of other European indices, as investors reassessed the risk of exposure to French assets.
Political Crossroads: 2027 Elections and the Specter of Moral Hazard
The backdrop amplifying distrust is the political paralysis and uncertainty regarding future leadership. President Emmanuel Macron’s government lacks a stable parliamentary majority, making it extremely difficult to pass the necessary spending cuts. The unrest has revealed this fragility: lawmakers must choose between responding to social pressure or imposing austerity that could further inflame the streets.
However, the real cloud hanging over the markets are the upcoming 2027 presidential elections. Polls show Marine Le Pen, leader of the far-right National Rally party, as the frontrunner, proposing tax cuts and reducing the retirement age to 60, despite the pension system already consuming an increasing portion of the budget. On the opposite end, radical left candidate Jean-Luc Mélenchon suggests that the central bank directly cancel the French debt it holds.
Macquarie analysts have characterized the market sentiment as a verdict of «guilt» on the direction of French presidential policy. Their base case does not predict imminent default, but they assign a close to 50% probability to a National Rally presidency that would further degrade France’s credit risk perception for the 2028 budget. The rating agency Scope Ratings downgraded France from AA- to A+ last month, warning that political fragmentation will complicate fiscal consolidation beyond the elections and weaken confidence in the country’s ability to stabilize its debt in the medium term.
Outlook: A Crucial Test for the ECB and the Euro
The ball is now in Frankfurt’s court. ECB President Christine Lagarde has made it clear: the solution to France’s debt issues «lies within the country itself», a warning that cools speculation about ECB intervention to contain widening spreads. The ECB’s anti-fragmentation tool (TPI) is designed for «unjustified and disorderly» tensions, but the source of the French movement—an acknowledged fiscal deterioration by rating agencies and underlying political uncertainty—hardly fits that category.
France faces a vicious circle: as yields rise, the cost of refinancing a debt exceeding one trillion euros becomes increasingly expensive, while the margin for social spending demanded by the public narrows. The government is already considering shifting towards short-term debt issuance, facing challenges in placing long-term paper in a market that distrusts its fiscal credibility ten years out. With the 2027 elections on the horizon and investor confidence shattered, the French bond has ceased to be the refuge it once was and has become a thermometer for one of the most severe confidence crises the eurozone has faced since 2012.
The Citizen
Obtén tu Pasaporte y apoya a El Ciudadano
Elimina la publicidad, accede a contenido exclusivo y sé parte de la comunidad.
Cancela en cualquier momento · Sin permanencia
Artículos Relacionados
China Denies Claims of Industrial Overcapacity and Publishes Defense Document on Development Model
Hace 3 meses